

High REVS Performance provides mobile ECU remapping across Tamworth and Staffordshire, which means the work can be completed at your home or workplace without losing a day at a garage. Before booking, though, the remap insurance impact deserves a straight answer. A Stage 1 remap is a vehicle modification, and in most cases your insurer needs to know about it.
That does not automatically mean a huge premium increase, refused cover or a complicated process. It means treating the remap as part of your vehicle’s declared specification. The right approach is simple: choose a safe, custom-written calibration, keep the details of the work, and tell your insurer before or as soon as the modification is fitted.
What insurers mean by an ECU remap
An ECU remap changes the calibration held in the engine control unit. Depending on the package selected, it can improve low-down torque, throttle response, overtaking performance or fuel economy. At High REVS Performance, Eco, Balanced and Stage 1 Power remaps are written for the individual vehicle and kept within sensible manufacturer tolerances, rather than relying on a generic file loaded onto every similar model.
From an insurer’s point of view, the key issue is not whether the remap was carried out on your drive, in a workshop or at a dealer. It is that the vehicle’s performance characteristics have changed from standard. A Stage 1 Power remap may increase torque and horsepower. An Eco remap may prioritise more efficient driving, but it is still a change to the engine calibration and should be disclosed if your policy terms require all modifications to be declared.
The exact wording varies between insurers. Some ask about any engine management changes, while others have a broad question covering modifications from the manufacturer’s standard specification. If there is any doubt, ask the insurer directly and make a note of the answer, including the date and the adviser’s name.
The real remap insurance impact on your premium
There is no fixed price increase for a remap. One insurer may make a small adjustment, another may offer cover with no change, and a third may decide the vehicle falls outside its underwriting criteria. Your age, postcode, claims history, annual mileage, vehicle model, occupation and where the car is kept can all matter as much as the remap itself.
A sensible Stage 1 calibration on a daily-driven diesel is often viewed differently from a heavily modified performance car with several undeclared upgrades. Insurers assess overall risk, not merely a single figure for additional power.
For many drivers, the bigger issue is finding an insurer that understands modifications rather than accepting a standard policy that is not designed for them. A modified-car or specialist insurer may be more appropriate where a mainstream provider will not cover a remap. Comparing on a like-for-like basis matters here: check excesses, agreed value where relevant, windscreen cover, recovery, business use and any mileage restrictions rather than focusing only on the annual price.
Do not assume that an economy-focused calibration avoids the question. If it changes ECU settings, declare it. The potential saving in fuel is worthwhile only if the car remains correctly insured.
Why undeclared remaps create avoidable risk
Some owners worry that contacting their insurer will immediately make cover unaffordable, so they say nothing. That is the risky option. If a vehicle is stolen, damaged or involved in an accident, an undeclared remap can complicate a claim and may affect how the insurer handles it. Outcomes depend on the policy wording and the circumstances, but it is not a position worth putting yourself in for the sake of one phone call.
Transparency also protects the owner if the vehicle is sold later. A buyer should know that the ECU has been remapped, what type of calibration was fitted and whether it can be returned to standard. Clear paperwork shows the work was professionally carried out, not an unknown modification with no record behind it.
A proper remap is not a shortcut around vehicle responsibility. It should sit alongside suitable servicing, fault-free operation and honest insurance disclosure. This is particularly relevant for diesel vehicles, where an existing DPF, EGR, boost or sensor fault must be diagnosed rather than hidden behind a calibration change.
A typical Staffordshire diesel scenario
Take a 2017 Volkswagen Transporter 2.0 TDI used by a self-employed tradesperson around Tamworth, Lichfield and the wider Staffordshire area. It is loaded with tools most weekdays, feels flat when joining the A5, and regularly covers motorway miles. The owner wants stronger mid-range pull without turning the van into a hard-driven project.
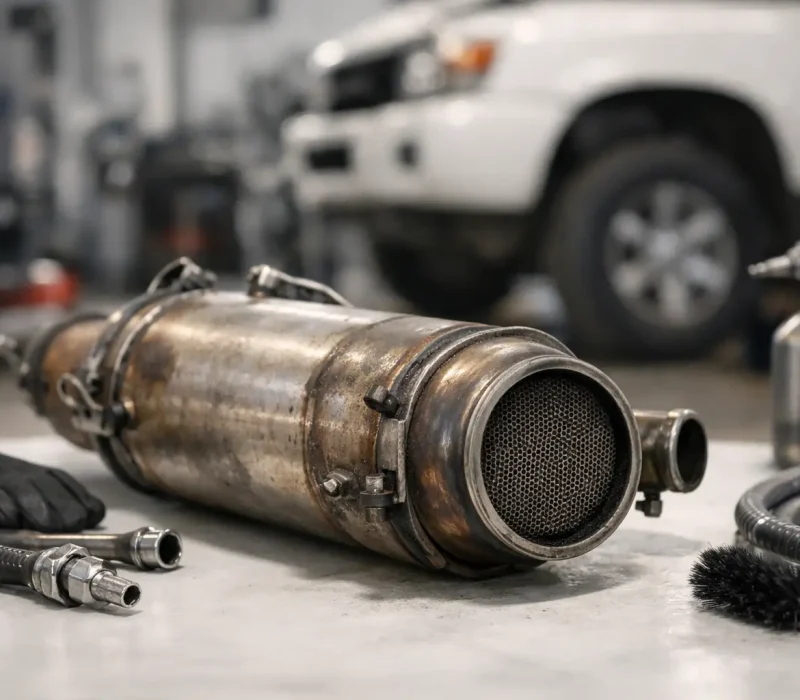
A mobile on-site diagnostic appointment comes first. If there are stored boost-control faults, excessive soot loading or DPF pressure readings that point to a blockage, those faults need dealing with before any remap is considered. In some cases, a DPF chemical clean restores the airflow and regeneration performance that the owner thought had disappeared forever. Remapping a van with an unresolved fault is not good practice and can make diagnosis harder later.
Once the vehicle is mechanically sound, a Balanced or carefully selected Stage 1 Power remap can give the Transporter stronger torque for loaded driving and more relaxed overtaking. The owner then contacts the insurer and declares an ECU remap, explaining that it is a professionally installed Stage 1 calibration. The insurer may ask for the new power output, the tuning company’s details or written confirmation of the modification. That is a normal part of the process.
The outcome could be a revised premium, no additional charge, or a move to a provider better suited to modified vans. What matters is that the business vehicle remains properly covered while delivering the improvement the owner actually needed.
What to tell your insurer before booking
You do not need to be an engine calibration expert to make a clear disclosure. Tell the insurer you are planning an ECU remap and ask what information they need before the work is completed. Be precise about the intended package, particularly if it is a Stage 1 Power remap rather than an economy-led option.
Most insurers will want some combination of the vehicle registration, make and model, estimated power and torque increase, the type of remap, and confirmation of any other modifications already fitted. If the vehicle is used for business, carries tools or tows a trailer, mention that too. It helps the insurer assess the vehicle as it is genuinely used.
Ask these practical questions during the call:
- Does the policy cover a professionally fitted ECU remap?
- Is there an administration fee or premium adjustment?
- Do you need written evidence of the new power and torque figures?
- Will the modification affect breakdown cover, legal cover or agreed-value terms?
- Does the insurer require notification before the work is carried out?
Get the answer confirmed by email or through your insurer’s online account where possible. A verbal assurance is useful, but written confirmation is easier to refer back to at renewal or if staff change.
Professional work makes disclosure easier
The insurance conversation is easier when you can describe the work clearly. A custom-written remap completed with genuine professional tools gives you a defined service to disclose, rather than vague claims about a vehicle being “chipped”. It also avoids the uncertainty that comes with cheap plug-in tuning boxes, unknown files and modifications installed without checking the vehicle’s condition first.
At High REVS Performance, the mobile process is built around convenience without skipping the technical checks. The vehicle can be assessed on site, faults can be identified before tuning, and the selected calibration can be matched to how you actually drive. A commuter covering long A-road and motorway journeys may prefer an Eco or Balanced map. A towing driver or loaded van owner may benefit more from usable mid-range torque. Neither choice removes the need to notify the insurer, but choosing the right service avoids paying for a result that does not suit the vehicle’s role.
Do not confuse a remap with emissions tampering
A legitimate ECU remap should not be confused with removing or disabling emissions-control equipment. DPF removal and emissions-delete software can create legal, MOT, reliability and insurance problems. If a diesel has warning lights, limp mode or repeated failed regenerations, the proper route is on-site diagnostics followed by suitable repair work, such as DPF chemical cleaning where the vehicle’s condition supports it.
This distinction matters to insurers and to owners. Restoring a blocked DPF and fitting a safe calibration to a healthy engine is very different from trying to mask faults or bypass emissions systems. Good tuning starts with a vehicle that is running correctly.
If you are considering a Stage 1, Eco or Balanced remap and want the figures and process explained clearly before you call your insurer, book a mobile ECU remap or on-site diagnostic appointment with High REVS Performance. You will get a service matched to your vehicle, your driving and the practical reality of keeping it properly insured.